Hail Damage or Total Loss? How Insurance Decides and What You Can Do About It
Your car took a beating in a hailstorm. Every panel is dented. Now you are waiting to hear back from the insurance company, or maybe you already got the call that they want to total it.
The car still drives fine. The mechanicals are untouched. It feels wrong that a dented roof could mean the end of a car you have loved for years. Fair to feel that way. The hail damage repair vs total loss question is one of the hardest calls in the aftermath of a serious storm, and honestly, the owner side of the story rarely gets told.
We have worked alongside plenty of customers through this exact moment in the Killeen and Harker Heights area. Some got the call they hoped for. Some did not.
Either way, understanding how the decision gets made and what you can do about it makes the whole situation less confusing. This article walks through the math the insurer uses, what to do if you disagree, and what your options look like on both sides of that decision.
How the Total Loss Decision Actually Gets Made
Insurance companies do not total a car because it looks bad. They total it because the numbers work out a certain way.
The basic math is straightforward. The insurer compares two figures: the estimated cost to repair your car and its actual cash value before the storm hit. If the repair estimate crosses a certain percentage of that pre-storm value, they call it a total loss. The specific percentage varies by state and by insurer, but it is a real threshold that triggers the decision.
For hail damage, this math often lands close to the line. Full-vehicle hail on an older car can easily push repair costs above the threshold because so many panels need work. A newer car with the same damage may fall under the threshold because its value is higher.
None of this is personal. It is a formula the adjuster is required to apply. But it can still feel arbitrary when your car drives fine and looks fixable.
What "Actual Cash Value" Means for Your Car
Actual cash value is what your car was worth right before the storm, based on its age, mileage, condition, and market. It is not what you paid for it, and it is often less than what you owe on a loan.
This is where things get uncomfortable for a lot of drivers. If your loan balance exceeds the actual cash value, a total loss payout may not cover what you owe. Gap insurance handles this situation if you have it, but not everyone does.
Before assuming the total loss offer is what the car is worth, it is worth doing your own research on comparable vehicles in your local market. This is one area where the initial offer sometimes has room for negotiation.
When the Insurer Calls It Repairable
If the numbers land on the repair side, your car goes to a shop and gets fixed. For a lot of drivers, this is the preferred outcome since it means keeping the car they know.
Here is what to think about when the call goes this way:
- Where the work gets done. Some insurers steer to specific shops. Shop-of-choice rules vary by state and by policy, so worth asking your insurer or checking your policy documents.
- The estimate quality. A rushed estimate misses damage. A shop that walks the car thoroughly catches more, which can adjust the total.
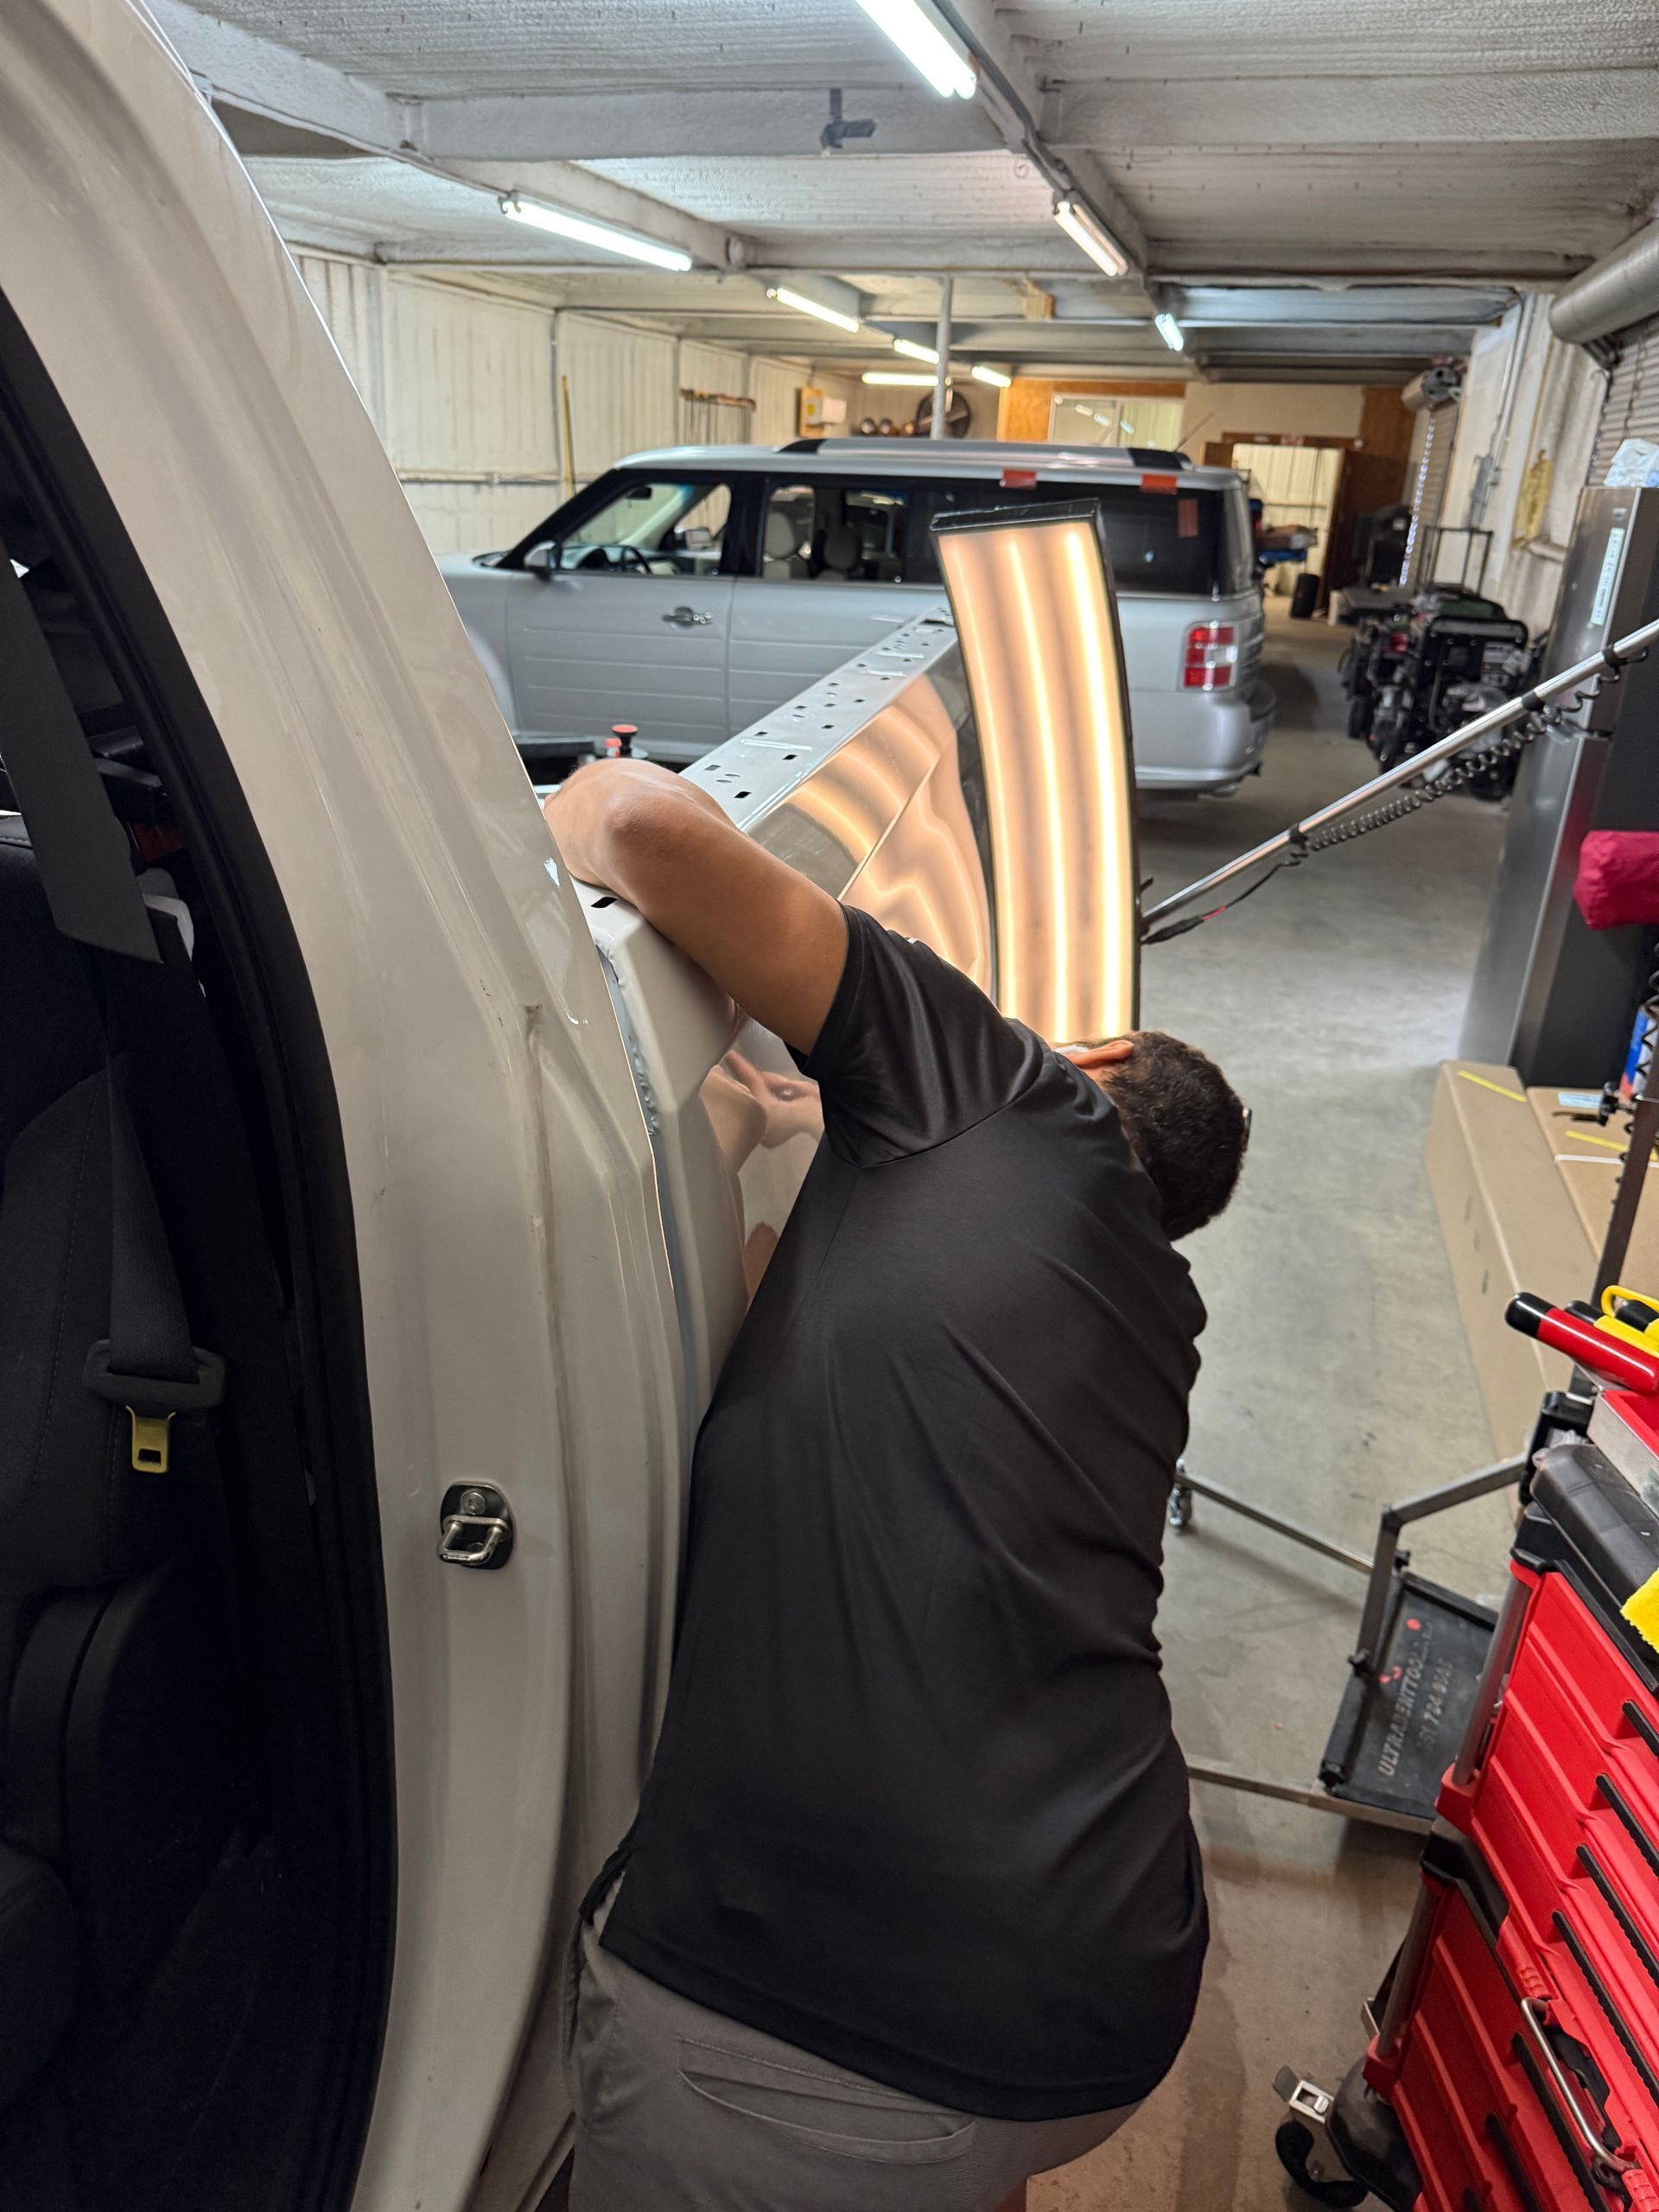
- Paintless vs traditional repair. For hail with intact paint, paintless dent repair preserves your factory finish. For panels where paint cracked, bodywork is needed. Our paintless dent repair page walks through when each fits.
- Deductible situation. You pay your deductible, and insurance handles the rest of the work the adjuster approves. In some cases, if the damage crosses a threshold, our shop may help with the deductible.
More on the process side is available on our hail repair insurance claim page.
When the Insurer Calls It a Total Loss
If the numbers land on the total loss side, the insurer takes the car and pays you the actual cash value minus your deductible. You lose the car, but you get a check.
You then have choices to make:
- Take the payout and walk away. Buy a different car with the money.
- Buy back the vehicle. Most insurers will let you keep the car for a reduced payout, but the title changes to "salvage" or "rebuilt," which affects future value and insurability.
- Negotiate the actual cash value offer. If your research shows comparable vehicles are worth more, present that evidence and ask for a revised offer.
None of this is easy when you are also dealing with the loss of a car you liked. Take a breath, do the research, and know that you have options.
What to Do If You Disagree With a Total Loss Decision
Most articles skip this part. If the insurer totals your car and you think that is the wrong call, you have options. Not guarantees, but options.
- Ask for a second estimate. Have another shop look at the car and write their own repair estimate. Sometimes a second look uncovers work that could be handled a different way or at a different cost.
- Question the actual cash value. Pull local comparables from listings, dealer inventories, and appraisal services. If your car is worth more than the offer, document it.
- Request the total loss threshold formula. Ask the insurer to explain exactly how they reached the decision. Understanding the math helps you know where to push.
- File an appeal. Most insurers have an internal appeals process for total loss decisions. Ask about it.
- Consult your state insurance department. State insurance regulators oversee claim decisions. If you feel the process was not fair, they can be a source of guidance.
None of this is legal advice, and none of it guarantees the decision gets reversed. But these are the paths people take when they disagree with the initial call.
When Repair Is Possible but the Insurer Wants to Total It
Sometimes a car that could be repaired well ends up totaled because the estimate is high or the actual cash value is low. If you know the car can be brought back, one option is to buy it back from the insurer and repair it yourself.
This is not for everyone. The salvage title stays with the car, which reduces resale value and may affect insurance rates going forward. But for someone who intends to hold onto the car for years and does not care about resale, it can make sense.
Before choosing this path, weigh the reduced payout, the cost of repair, and the future salvage title implications. It is not a decision to make in a hurry.
When to Just Take the Total Loss
On the other side, sometimes accepting the total loss is the smart call, even if you love the car.
- The car has significant miles or age already
- Frame or structural damage exists in addition to the hail
- You do not want to deal with a salvage title later
- The payout is enough to put toward something you have wanted anyway
There is no shame in taking the payout. It is often the cleanest path forward.
Stop In and We Can Talk You Through It
Insurance decisions are not something we make for you, but we can look at the damage, write an honest repair estimate, and help you think through the options. If the insurer wants to total it and you are not sure, a second opinion from a shop that does this work every day can be useful.
Reach out through the contact page or head over to the Harker Heights Ceramic Coatings home page. Central Texas drivers can also visit our Killeen paintless dent repair page.
Frequently Asked Questions
What percentage of a car's value triggers a total loss decision?
The threshold varies by state and by insurer. Some states set the percentage in regulation, while others let insurers set their own.
It is usually a percentage of the car's actual cash value. If the repair estimate crosses that line, the car is called a total loss. Your insurer can explain the specific number they use.
Can I still drive my car after a total loss decision?
Depends on the situation and your state. If the car is drivable and you buy it back, you may be able to keep driving it once the title work is done. Most states require the car to pass a safety inspection before it can be re-titled and driven legally. Check with your state DMV or your insurer for specifics on your case.
Will my rates go up after a hail claim?
Weather-related claims and claims where the driver was at fault are usually handled differently by insurers, so hail alone may not raise your rates. But every policy is different and every insurer has its own rules. Best to raise it with your own agent if it matters for your situation.
If I buy back my totaled car, will insurance cover it going forward?
Some insurers will insure a rebuilt-title car but only with limited coverage. Others may not insure it at all. Worth checking with your insurance company before you decide to buy back the car, since limited coverage changes the math.
Can I get a second opinion on a repair estimate?
Yes, and it is often a good idea when you disagree with the insurer's decision. Drive over and we can put together an independent estimate. Sometimes the second estimate lands lower than the first because a good shop uses paintless dent repair where the first estimate assumed bodywork. That can shift the total under the threshold.